California state income tax
One formula instead of ten brackets
Today California taxes income in ten steps, like a ladder. This page replaces the ladder with one smooth formula that cuts taxes for most people and keeps rates close to today's for incomes under $1 million, plus a surtax on income above $1 million. It also taxes loans against unrealized gains, so people who borrow against their stock instead of selling it still pay tax on the gain. The new revenue would close the state budget deficit, keep CalFresh food benefits whole, and restore Medi-Cal coverage, and the borrowing rule could help pay for affordable homes and free college.
Rate on your next dollar today's 10 brackets and the proposed formula
Single filer, taxable income, log scale (each mark is ten times the last). Today's step points follow published 2026 tables, which differ slightly by source. Revenue applies the settings to FTB tax-year 2022 returns, adjusted to current dollars, and scales the change to the LAO's $149.6 billion income tax forecast for 2028–29. The response setting says how much high earners cut the income they report, by moving, working less, or shifting income: Low matches studies finding few people leave California over taxes; High matches a 2024 study of the 2012 rate increase. Nothing is counted from taxing borrowed gains.
Who pays more, who pays less average change in state income tax per return, by income class
Hover over or tap a bar for details.
In the “by number of returns” view, each bar is as wide as its share of California's 17 million tax returns, so you see how many people each change touches. In the “by income” view, bars sit on an income scale like the chart above. Bar height uses a scale where each gridline is ten times the one before, so a $1,000 cut and a $1 million increase both stay visible. Figures are averages for each income class from Franchise Tax Board data for tax year 2022, adjusted to current dollars; people within a class differ.
How steady is the money? share of state income tax paid by returns with income over $1 million
Income at the top swings with the stock market, so a plan that leans on it more also swings more. To keep that from upsetting the budget, the plan would count on the surtax only up to its average over the past several years, and send anything above that average to the Rainy Day Fund.
The formula
rate on next dollar = 18% × income ÷ (income + $150,000), plus 16 points on income above $1 million
Total tax works out to top rate × (income − halfway × ln(1 + income ÷ halfway)) + surtax × (income − $1 million, if positive), so the Franchise Tax Board can still print a lookup table for people who file on paper.
Three numbers set the whole tax: the formula's top rate, the halfway income, and the surtax above $1 million. Below $1 million there are no steps, so a raise always means a slightly higher rate on the extra money, never a jump. A person with low income pays almost nothing. At the proposal's settings, nobody under $1 million sees the rate on their next dollar rise by more than about 3.6 points, and most people see it fall. Above $1 million, the surtax adds a fixed number of points, the way the existing 1% mental health surtax does.
Keeping up with prices
Today the state adjusts each bracket every year for inflation, using the California Consumer Price Index from June to June. With the formula, the state adjusts two dollar amounts: the halfway income and the $1 million surtax line.
halfway income this year = $150,000 × (CCPI this June ÷ CCPI June 2026)
Because both amounts move together, the whole schedule shifts with prices. If prices rise 3%, the halfway income becomes $154,500 and the surtax line $1,030,000, and someone whose pay also rose 3% pays the same share as before. The top rate never changes unless lawmakers or voters change it. A state could instead tie the halfway income to median wages, so that real raises do not slowly push people up the ramp.
Where the money comes from, and where it goes billions of dollars a year at the current settings
The left side shows the extra tax paid by income classes that pay more. The right side shows where it goes: first the tax cuts for everyone who pays less, then the needs listed below.
What it pays for
Even after this year's budget, the Legislative Analyst's Office expects California to spend $8 billion to $10 billion a year more than it collects through 2029–30. The federal H.R. 1 law also shifts food aid and health costs to the state. Keeping CalFresh food benefits whole costs about $4 billion a year, and undoing the planned Medi-Cal cuts to immigrant coverage and community clinics costs about $4 billion more.
- Close the deficit: about $10 billion a year
- Keep CalFresh whole: about $4 billion a year
- Restore Medi-Cal coverage and clinic payments: about $4 billion a year
- Build 90,000 more affordable homes a year: about $15 billion a year
- Make public college debt-free: about $4.5 billion a year
- Schools and community colleges: about $12 billion a year (Prop. 98 mandate)
- Total: about $30 billion a year
Over ten years, 900,000 more homes would mean about 6% more homes in the state. Based on the Legislative Analyst's estimates, that would leave rents about 3% lower and home prices about 7% lower than otherwise. For a renter paying the median California rent of $2,104 a month, that is about $760 a year saved.
Debt-free college would pay what resident undergraduates at community colleges, Cal State, and the University of California still owe for tuition and living costs after federal grants, a family contribution, and part-time work. The Legislative Analyst estimated this at $3.3 billion a year in 2017, about $4.5 billion in today's dollars, with about two-thirds going to community college students. Students could finish a degree without loans. Like the housing money, it would sit in its own fund.
The proposal pays for the first three items and the schools' share. Homes and college are options you can add with the “Pay for” boxes above; the borrowing rule, which none of these figures count, is the most likely way to pay for them. Revenue uses the response setting chosen above.
Gains you borrow against
Very rich people often never sell their stock. Instead they borrow against it, live on the loans, and pass the stock on at death, when the untaxed gain is wiped out. If you can spend the gain by borrowing against it, you can pay tax on it. One way to do that:
- When you borrow against stock or property that has gone up in value, the amount you borrow counts as income that year, up to your untaxed gain.
- The first $250,000 a year per person is free (indexed like the halfway income), so ordinary borrowing is not affected.
- Home loans on your main home, student loans, car loans, and credit cards do not count.
- The gain you paid tax on is marked as taxed, so you never pay twice when you later sell.
- The counted amount goes through the same formula as any other income.
This matches one of three options studied by the Yale Budget Lab for the federal tax. The other two are a 10% withholding on such loans, credited later, and a small yearly charge on the loan balance.
Try an income
Borrowed amounts count only above the $250,000 free amount, and only up to the untaxed gain (this calculator assumes the gain is at least that large). Next-dollar rates add the state rate, the 2026 federal income tax bracket, and Medicare tax (1.45%, plus 0.9% on wages over $200,000 single or $250,000 joint); they are approximate and leave out Social Security tax, which stops at $184,500 of wages. Head of household filing is not modeled.
What it means for a monthly budget typical households at the current settings
Taxable income, after deductions. Couples use the joint-filer tax tables. When the housing option is in the package, rent savings assume a renter paying the California median rent of $2,104 a month, about 3% lower once the 900,000 new homes are built, in roughly ten years.
Why this matters
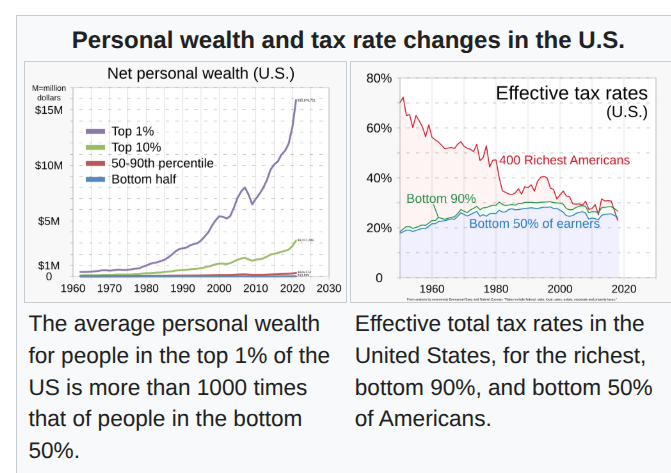
Across the U.S., the richest people have pulled far ahead in wealth, mostly as gains they never sell. At the same time, the share of income they pay in total taxes has fallen to about what everyone else pays. A smooth ramp that keeps rising at the top, plus a tax on borrowed gains, reaches the money that today's ladder misses.
What critics say
California already has the highest top state income tax rate in the country, and critics say higher rates push high earners to move away. They also say a loan is not income because it must be paid back, that the rule needs the value and purchase price of every asset at the time of borrowing, and that people could move out of state before they borrow. With the surtax, the combined federal and state income tax on the next dollar of income above $1 million would be about 70%, which raises the risk that the highest earners move or report less income; under the middle response setting above, the plan raises almost nothing. Voters also approved Proposition 42 in November 2026, which bars new state taxes on owning financial assets, so the borrowing rule would need to be framed and defended as a tax on a realization event, borrowing, rather than on ownership. Leaning on a few very rich people also makes the state budget swing with the stock market. Studies disagree on how many people actually move because of taxes.
Sources: FTB on indexing, Yale Budget Lab on borrowing against gains, 2026 California brackets, LAO 2026-27 spending plan, LAO on H.R. 1 CalFresh changes, FTB income distribution data, LAO on housing costs, California Housing Partnership 2026, Enterprise pipeline brief, LAO on debt-free college.
Send your own letter
You can send this same request to your own representatives. The letter below is a template: fill in every highlighted field before you send it.
- Find your representatives at findyourrep.legislature.ca.gov. Enter your home address and note your Assemblymember and State Senator and their district numbers.
- Look up their Capitol suite numbers and email addresses in the Secretary of State's rosters for the Assembly and the Senate. Assembly addresses usually look like assemblymember.lastname@asm.ca.gov, and Senate addresses like senator.lastname@senate.ca.gov, but check the roster.
- Copy the letter into your email program and replace each highlighted field. If your Assemblymember is Chair Gipson or your Senator is Chair McNerney, delete the duplicate address block. If your own legislator lost the November 3rd election, delete the congratulations sentence.
- Add one or two sentences of your own about how taxes, food aid, health coverage, or housing costs affect you. A personal line gets more attention than a form letter.
- Save the two figures in the letter (right-click or long-press each image) and insert them inline where they appear, or attach them.
- Email it to your two legislators and the two committee chairs, and copy the Governor's staff, using the lists below.
- Paste the text into the Governor's form at gov.ca.gov/contact, which accepts no attachments, and into Governor-Elect Becerra's form at xavierbecerragovernor.com/contact-us.
- For extra weight, print the letter from your email program and mail it to the Capitol addresses shown.
Committee chairs are reassigned when the Legislature reorganizes in December 2026. Before sending in 2027, check the Assembly and Senate Revenue and Taxation committee pages.
Subject line
Constituent request: replace income tax brackets with one indexed formula and tax borrowing against unrealized gains
To (add your own two legislators)
assemblymember.gipson@asm.ca.gov, senator.mcnerney@senate.ca.gov
Cc
nathan.barankin@gov.ca.gov, christine.aurre@gov.ca.gov, joe.stephenshaw@dof.ca.gov
[Your full name]
[Street address]
[City], CA [ZIP]
[Your email]
[Your phone number]
[Date]
The Honorable [Your Assemblymember]
Member, California State Assembly, [number] District
1021 O Street, Suite [number]
Sacramento, CA 95814
Email: [assemblymember email]
The Honorable [Your State Senator]
Member, California State Senate, [number] District
1021 O Street, Suite [number]
Sacramento, CA 95814
Email: [senator email]
The Honorable Mike A. Gipson
Chair, Assembly Committee on Revenue and Taxation
Member, California State Assembly, 65th District
1021 O Street, Suite 6210
Sacramento, CA 95814
Email: assemblymember.gipson@asm.ca.gov
The Honorable Jerry McNerney
Chair, Senate Committee on Revenue and Taxation
Member, California State Senate, 5th District
1021 O Street, Suite 6640
Sacramento, CA 95814
Email: senator.mcnerney@senate.ca.gov
The Honorable Gavin Newsom
Governor of California
Nathan Barankin, Chief of Staff, nathan.barankin@gov.ca.gov
Christine Aurre, Legislative Affairs Secretary, christine.aurre@gov.ca.gov
Luke Reidenbach, Chief Deputy Legislative Secretary (Revenue and Taxation)
Joe Stephenshaw, Director of Finance, joe.stephenshaw@dof.ca.gov
1021 O Street, Suite 9000
Sacramento, CA 95814
ALSO BY ELECTRONIC COPY TO gov.ca.gov/contact
The Honorable Xavier Becerra
Governor-Elect of California
BY ELECTRONIC COPY TO xavierbecerragovernor.com/contact-us
Re: Request for legislation replacing the personal income tax brackets with a single indexed rate formula and taxing borrowing against unrealized gains
Dear Assemblymember [last name], Senator [last name], Chair Gipson, Chair McNerney, Governor Newsom, and Governor-Elect Becerra:
Congratulations on your and your coalition's victory in the November 3rd election! I am a constituent of Assemblymember [last name] and Senator [last name] in [City], and I respectfully ask each of you to introduce, co-author, and support legislation in the 2027–28 session that makes three changes to the California personal income tax. I would also ask the Governor's office and the incoming administration to request estimates from the Franchise Tax Board and the Legislative Analyst's Office so the changes can be calibrated before introduction.
The problem. As Figure 1 shows, economists Emmanuel Saez and Gabriel Zucman estimate that the effective total tax rate paid by the 400 richest Americans has fallen from about 70 percent in 1950 to roughly the rate paid by the bottom half of earners, while the wealth of the top 1 percent has grown to more than 1,000 times that of the bottom half. California's own schedule has ten brackets with uneven spacing. For a single filer, one 9.3 percent bracket runs from about $70,600 to about $360,700, so a teacher and a senior executive face the same marginal rate, and the schedule stops rising at $1 million. The 10.3 to 12.3 percent rates also face expiration after 2030 unless voters or the Legislature act.
|
Figure 1. U.S. wealth and effective tax rates. Image: Wikipedia; tax-rate analysis by Emmanuel Saez and Gabriel Zucman. |
Request 1: One continuous rate formula in place of the brackets, plus a surtax above $1 million. I propose (see Figure 2) that the marginal rate on each additional dollar of taxable income y be:
rate = R × y ÷ (y + M)
Here R is the top rate and M is the "halfway income," where the rate is half of R. Total tax has an exact closed form, R × (y − M × ln(1 + y ÷ M)), so the FTB can still publish tables. Joint filers would use 2M, matching current practice of doubling brackets. There are no cliffs or flat stretches, and every raise is taxed at a slightly higher rate rather than a jump. With R = 18 percent and M = $150,000, the formula alone is roughly revenue-neutral, and it raises the rate on the next dollar by no more than about 3.6 points for anyone under $1 million while lowering it for most taxpayers. To meet the needs described below, I propose adding a surtax of 16 percentage points on taxable income above $1 million, indexed like M, which works the same way as the existing 1 percent Proposition 63 surtax. Every single filer with taxable income below about $304,000 (about twice that for joint filers) would pay less tax than today: about $4,208 instead of $5,842 at $100,000. Filers above that would pay more: about $64,545 instead of $56,408 at $600,000, about $125,004 instead of $104,395 at $1 million, and about $3.1 million instead of $1.3 million at $10 million. About 3 of every 100 returns would pay more. I ask that the FTB and LAO score these settings, including behavioral responses, before introduction.
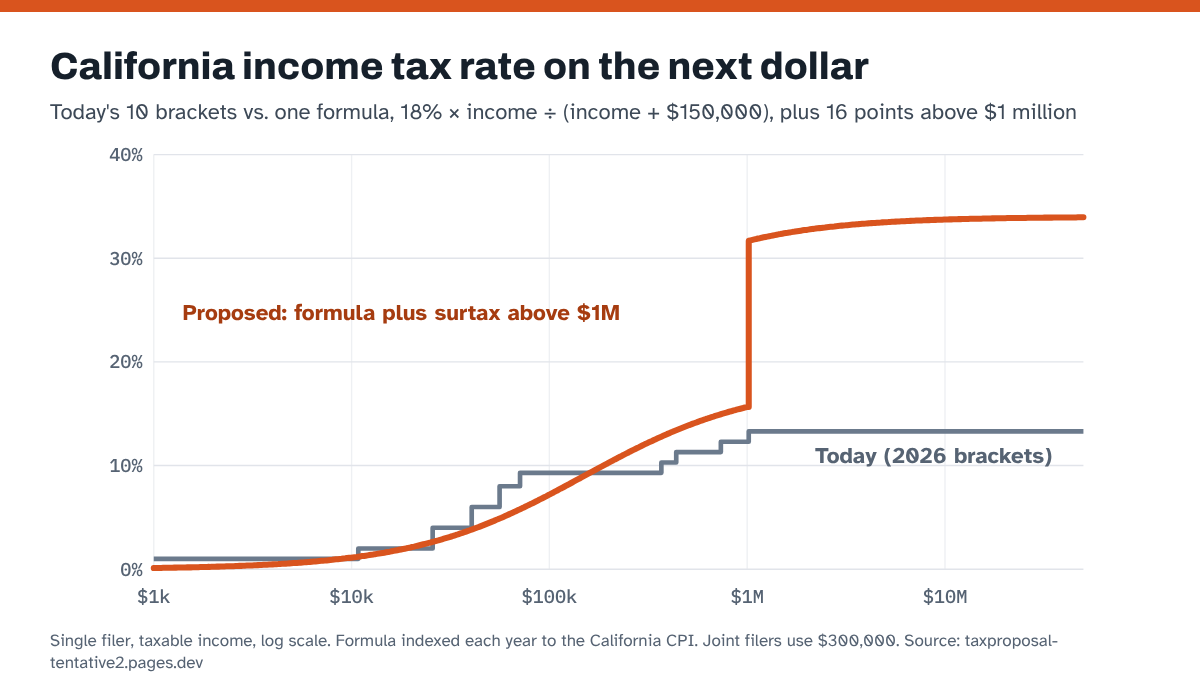
Figure 2. California tax rate on the next dollar, today and under the proposed formula (R = 18%, M = $150,000, plus a 16-point surtax above $1 million). |
Request 2: Automatic indexing. Each year, M and the $1 million surtax threshold would be multiplied by the ratio of the California Consumer Price Index for June of that year to June 2026, the same June-to-June measure the FTB already uses for bracket indexing. This keeps the whole schedule constant in real terms. The rates would change only by legislation or vote. I would also welcome analysis of indexing M to California median wages instead, which would keep real wage growth from moving households up the schedule.
Request 3: Tax gains that are borrowed against. Many of the wealthiest households avoid tax by holding appreciated assets, borrowing against them to fund consumption, and passing them on at death, when the gain is erased. If a gain can be spent through a loan, it can bear tax. I propose that loans secured by appreciated assets be treated as realizing gain, up to the borrower's untaxed gain, above an exemption of $250,000 per person per year indexed with M. Mortgages on a primary residence, student loans, auto loans, and credit cards would be excluded. The amount taxed would be added to basis so the same gain is never taxed twice, and the counted amount would pass through the same rate formula as other income. This follows the deemed realization option analyzed by the Yale Budget Lab for federal reform, and California already taxes capital gains as ordinary income, so the change fits our system. Rules on part-year residents and out-of-state lenders would be needed to prevent avoidance. Because voters approved Proposition 42 this month, which bars new state taxes on owning financial assets, I ask that Legislative Counsel confirm this rule taxes a realization event, borrowing, much as the federal constructive-sale rule in Internal Revenue Code section 1259 does, rather than ownership.
What this would pay for. Even after this year's budget, the Legislative Analyst's Office projects operating deficits of $10.4 billion in 2027–28, $8.7 billion in 2028–29, and $8.3 billion in 2029–30, and it has recommended at least $10 billion in ongoing solutions. Those figures do not restore what H.R. 1 takes away. For CalFresh, the state's share of administrative costs rose in October 2026, adding about $480 million a year, and starting in October 2027 the state must pay up to 15 percent of benefits, about $2 billion a year at our recent error rate of nearly 11 percent. Keeping benefits whole for families cut by the new work-time limits and eligibility rules brings the CalFresh need to about $4 billion a year, within the Department of Social Services' estimate of $2.3 to $5.1 billion in lost federal CalFresh funding. For Medi-Cal, the enacted budget saves about $3 billion a year by 2029–30 by restricting coverage for immigrants, cuts community clinic payments by about $1 billion starting July 2027, ends adult dental benefits, and lowers the asset limit, and the administration expects 1.3 million people to leave Medi-Cal by 2029–30. Restoring the immigrant coverage and clinic payments alone costs about $4 billion a year.
Further revenue, such as from the borrowing rule in Request 3, which I have not counted, could also make housing cheaper. California funded about 23,400 new affordable homes in 2025, about a fifth of the Roadmap Home goal of 119,287 a year, and nearly 40,000 shovel-ready affordable homes are waiting for money. State subsidy averages about $170,000 per affordable rental home, so funding 90,000 more each year would cost about $15 billion a year. That is the midpoint of the 70,000 to 110,000 additional homes a year that the LAO estimated California would have needed to keep its home prices rising no faster than the nation's. Over ten years it would add about 900,000 homes, or 6 percent more than the state's 14.9 million. Based on the LAO's estimates of how housing demand and rents respond to supply, I estimate home prices would be about 7 percent lower and rents about 3 percent lower than otherwise. For a renter paying the state median of $2,104 a month, that saves about $760 a year, and the households who move into the new homes would save far more. I propose that the housing share go to a dedicated fund, as the Proposition 63 mental health surcharge does, so it is spent only on housing.
Such revenue could also make public college debt-free. In 2017 the LAO estimated that covering every resident undergraduate's remaining costs at the community colleges, the California State University, and the University of California (tuition and living expenses, after federal grants, an expected family contribution, and part-time work) would cost about $3.3 billion a year on top of existing aid, or about $4.5 billion in today's dollars. About two-thirds of that would go to community college students. I propose a second dedicated fund for this purpose, so that students can finish a degree without loans.
| Close the projected operating deficit | $10 billion |
| Keep CalFresh benefits whole | $4 billion |
| Restore Medi-Cal immigrant coverage and clinic payments | $4 billion |
| Schools and community colleges | $12 billion |
| New revenue needed each year | $30 billion |
I applied the formula and surtax to the FTB's most recent published distribution of returns by income (tax year 2022, adjusted to current bracket dollars). Schools and community colleges receive about 40 percent of new General Fund revenue under the constitution, which is why the package above totals $30 billion. With no change in behavior, personal income tax liability would rise about 32 percent, or roughly $47.8 billion of the LAO's $149.6 billion personal income tax forecast for 2028–29. High earners will respond, however. If the income they report falls modestly, as most studies of migration suggest, the plan raises about $30.2 billion, just enough for the package. If the response is as large as one recent study of the 2012 rate increase found, the plan raises almost nothing. That is why I ask that the surtax phase in over two years while the FTB measures the response, and that surtax revenue above its multi-year average go to the Rainy Day Fund. None of these figures count revenue from taxing borrowed gains under Request 3, which the FTB should estimate separately.
Concerns I take seriously. Opponents argue that higher top rates encourage high earners to leave, that a loan is not income because it must be repaid, that valuing assets at the time of borrowing is burdensome, and that reliance on a small number of taxpayers makes revenue volatile. They also point out that with the surtax, the combined federal and state income tax on the next dollar of income above $1 million would be about 70 percent, which strengthens the risk that high earners move or report less income. Housing skeptics add that slower price growth reduces existing owners' gains, and that a nearly fivefold increase in subsidized building could exceed federal tax-credit and bond limits and construction capacity, raising the cost per home. Research on tax-motivated migration does not agree on the size of the effect. I ask that the LAO analysis address each of these, and that the new rates phase in over two years so revenue and migration can be measured.
Chair Gipson and Chair McNerney, I respectfully ask that your committees hold an informational hearing on these proposals early in the 2027–28 session, with testimony from the FTB and the LAO.
Governor-Elect Becerra, during the campaign you pledged to review tax code changes to offset federal health care cuts. I hope you will include this proposal in that review. Governor Newsom, I ask that your office help the incoming administration by requesting the FTB and Department of Finance estimates now, before the 2027–28 budget is drafted.
An interactive version with charts, adjustable R and M, and a calculator for any income is available here: California Tax Ladder.
Thank you for your consideration. I would be glad to meet with your staff and would appreciate a written reply stating your position.
Respectfully,
[Your full name]
Constituent, Assembly District [number] and Senate District [number]
[Your email]
[Your phone number]